
Goldman Sachs recently published an article titled “What’s the Lifetime Value of a Fan?”
This is a real article.
Nobody hacked Goldman Sachs. A 24-year-old analyst did not accidentally upload an internal document before being killed with a lacrosse stick in Connecticut. The firm would simply like to know the lifetime value of a fan.
One of its bankers explains the opportunity this way: you can become a fan on day one and remain one into your nineties. Sports businesses, he suggests, should think increasingly about the lifetime value of a fan, a customer and even a family.
There is something breathtaking about watching finance discover hereditary sports allegiance.
My grandfather loved the Yankees.
My father loved the Yankees.
I love the Yankees.
They have reviewed this touching intergenerational story and determined that we have excellent retention metrics.
This is roughly where sports are now.
Apollo Global Management has established Apollo Sports Capital and describes the sports ecosystem as a $2.5 trillion investment opportunity. The Los Angeles Lakers recently changed hands in a deal valuing the franchise at $12.5 billion, while the new ownership group reportedly presented investors with scenarios in which that value eventually climbs as high as $62 billion. The Yankees’ parent company accepted a $2.6 billion debt-and-equity financing package from Apollo Sports Capital. The NFL, historically resistant to institutional ownership, now permits approved private-equity funds to hold minority positions in franchises.
LIV Golf, meanwhile, entered Chapter 11 after Saudi Arabia's Public Investment Fund poured more than $5 billion into the league. A rescue proposal has produced one of the more beautifully American subplots in professional sports: its enormous accumulated losses may themselves possess tax value under the right restructuring.
Imagine spending five billion dollars attempting to reinvent professional golf and accidentally creating a coupon.
Something has changed.
THE BEAUTIFUL INEFFICIENCY
Money did not suddenly arrive in sports.
Please.
The ancient Romans were scalping tickets to watch men get eaten.
Professional sports have always been commerce attached to tribal identity. Owners wanted money. Players wanted money. Cities got extorted for stadiums. Television networks spent obscene sums on games. Wealthy men bought teams for many of the same reasons wealthy men buy vineyards despite knowing absolutely nothing about grapes.
What is different now is the level of optimization.
For most of sports history, a team was an extremely strange business because its customers could not be trusted to behave rationally.
You did not evaluate whether the Detroit Lions deserved another year of your patronage. You inherited the Detroit Lions in roughly the same manner you inherited your nose.
Nobody in Buffalo conducted an annual strategic review of whether remaining emotionally attached to the Bills continued to maximize household utility. Nobody in Cleveland assembled the children around the kitchen table and announced that, after reviewing management against relevant comparables, the family had elected to become Seahawks fans.
The product could be awful. Management could be incompetent. The stadium could smell like wet concrete and institutional mustard.
You came back.
That irrationality is the entire fucking thing.
Ownership was often irrational too. Teams were trophies, civic monuments, family heirlooms, ego vehicles and occasionally very expensive mechanisms for sitting next to Jack Nicholson. Some owners were brilliant stewards. Some were cheap. Some were despots. Some made decisions based on scouting. Others made decisions because a 6-foot-5 quarterback reminded them of a nephew who went to Dartmouth.
It was inefficient. So were the stadiums. So were the broadcasts. So were the fans.
And somehow this collection of inefficiencies produced something people loved with extraordinary intensity.
Finance has now looked at that intensity and asked the perfectly reasonable question: Why isn't this monetized better?
THE FAN IS AN UNDERSERVED REVENUE STREAM
The answer increasingly extends beyond charging existing fans more.
There is only so much premium seating, dynamic pricing, betting integration and subscription packaging you can bolt onto an American sports consumer who already spends every Sunday watching football.
Eventually growth requires finding somebody new.
Which is where the NFL becomes interesting.
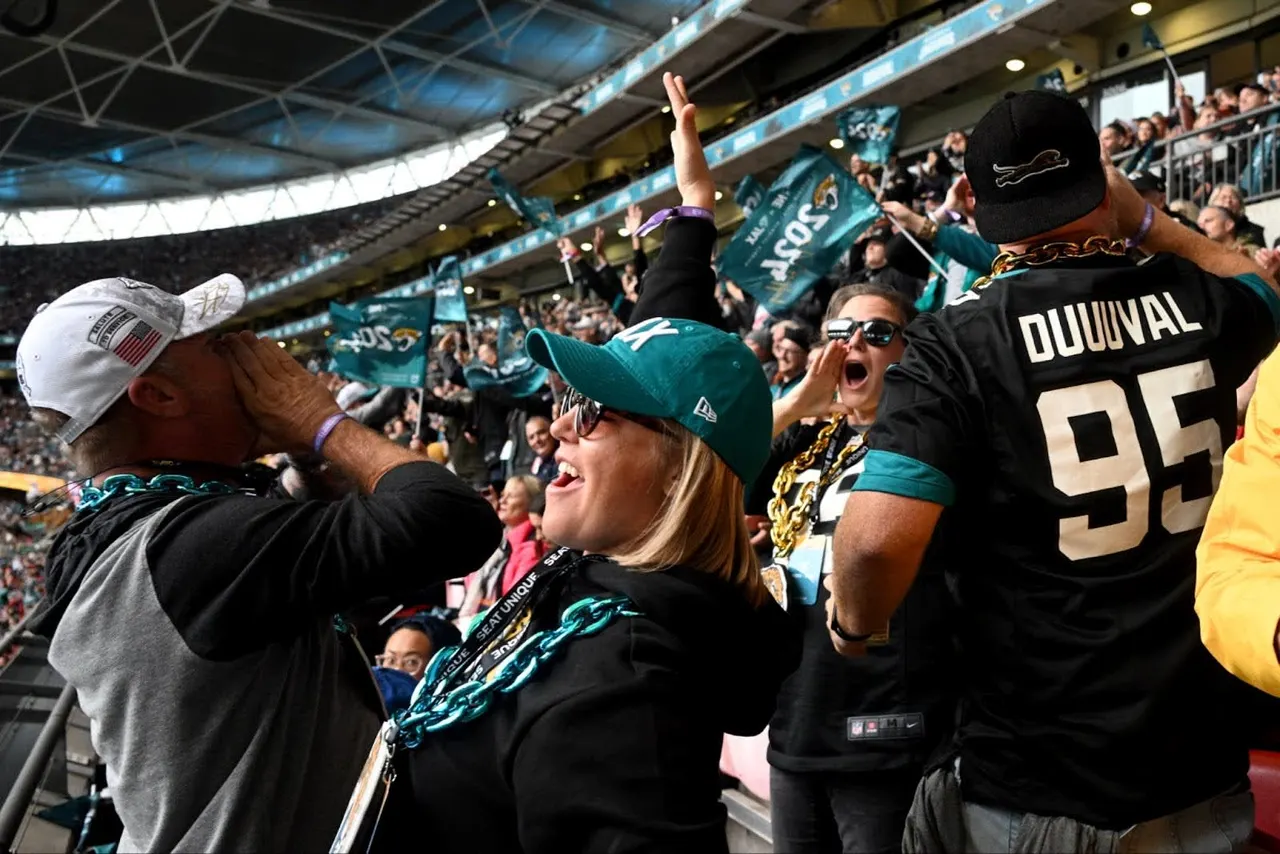
The league is playing a record nine regular-season games internationally in 2026, across four continents and seven countries. London gets three. Munich, Madrid and Mexico City get one each. Melbourne, Paris and Rio de Janeiro join the expanding footprint.
This is often described as growing the game. It is also customer acquisition.
The NFL has created a Global Markets Program assigning franchises commercial rights in foreign territories, where clubs can develop sponsorships, youth programs, merchandise sales and local fan bases.
The Cleveland Browns now possess international marketing rights in Nigeria.
Try explaining that sentence to Paul Brown without first administering something intravenously.
But the strategy is perfectly coherent. The NFL has become so dominant domestically that the next great pool of potential growth lives somewhere else.
You do not need every person in Munich to subscribe tomorrow. You need an eight-year-old in Munich to decide, for reasons nobody will ever fully understand, that he loves the Panthers.
Then you wait. A hat becomes a jersey. A jersey becomes a streaming subscription. Eventually there are tickets when Carolina returns to Germany, followed by another generation repeating the same financial and emotional mistakes.
Suddenly the international game is not a novelty. It is the beginning of a relationship.
Which brings us back to the Yankees.
Three generations of one family loving the same team is sentimental when viewed from the bleachers. From thirty-eight floors up, it is extraordinary retention.
The NFL has begun running out of Americans who don't already have a team. Fortunately, Earth contains several billion people who have not yet developed an irrational attachment to one.
This is the central asymmetry of modern sports economics: You cannot manufacture another Packers. You can manufacture another Packers fan.
The supply of elite franchises is fixed by design. The potential supply of emotional dependence is global.
And streaming makes the old geographic limitations less relevant. A league once needed television distribution to reach a foreign fan intermittently. Now it can maintain that relationship every week, sell direct subscriptions, personalize content, gather behavioral data and turn a Sunday afternoon curiosity into an always-on commercial relationship.
The international game gets the customer in the door. The streaming service makes sure he never really leaves.
None of this is evil. If people in Brazil, Germany, Spain or Australia genuinely fall in love with football, good. The point is not that expansion is sinister.
The point is that the same irrational loyalty that once made sports economically strange has become the industry's most attractive feature.
Unfortunately, many of the things fans treasure are valuable precisely because nobody has successfully optimized them yet.
The cheap seat. The weird local sponsor. The ugly stadium in the middle of town. The bartender who has watched every Mets game since 1976 and believes several Dominican relief pitchers have personally betrayed him.
Finance calls these things opportunities. Fans occasionally call them memories.
YOUR CITY IS ALSO IN THE PORTFOLIO
Franchise financialization gets stranger because the underlying asset is not merely a team.
It is often a legally protected scarcity asset attached to civic identity while possessing the ability to threaten its host city with relocation.
Try putting that in a normal investment prospectus.
Fans experience a franchise as part of the city. Owners necessarily experience it, at least partly, as property.
Those two facts coexist peacefully until somebody wants a new stadium. Then everybody learns very quickly who owns what.
A franchise can say: We belong to Chicago. Also, Indiana has called.
This is not hypocrisy so much as negotiating leverage.
And as franchise values rise, the stadium itself becomes only one piece of the investment. The surrounding district can include hotels, restaurants, offices, luxury housing, retail, parking and entertainment—a second portfolio wrapped around the first.
Your cherished civic institution has become vertically integrated.
The tailgate is now a mixed-use development strategy.
THIS IS NOT AN ANTI-CAPITALISM COLUMN, UNFORTUNATELY
Here is where the argument becomes annoying.
Institutional capital is not automatically bad for sports.
Some franchises desperately need professionalization. Some family ownership groups have spent decades demonstrating that hereditary wealth is not a reliable substitute for managerial competence. High valuations also make it increasingly difficult for individuals to purchase teams without outside capital.
There will be excellent institutional owners and disastrous family owners.
The private-equity people do not necessarily arrive Monday morning and tell Sean McVay that special teams has been outsourced to Hyderabad.
The issue is not private equity bad. That is too easy.
The issue is what happens when sports organizations begin optimizing around a broader definition of success.
A championship is success. But so is operating profit, franchise appreciation, sponsorship growth, media-rights expansion, premium seating, real-estate development, international customer acquisition and higher revenue per fan.
Once an asset costs $12.5 billion, appreciation stops being a pleasant side effect.
Nobody purchases something for $12.5 billion hoping someday it will be worth $11 billion and everyone had a nice time.
THE $62 BILLION BASKETBALL TEAM
This is why the Lakers number matters.
Not $12.5 billion. $62 billion.
That is reportedly the upper scenario presented to investors for what the franchise might someday be worth.
It may never happen. A financial model is essentially astrology for men who own quarter-zips.
But the number tells us what ownership believes the asset could become.
And once you believe a basketball team can become a $30 billion or $60 billion enterprise, the behavior follows naturally.
You search for revenue. You professionalize every function. You reconsider pricing. You expand internationally. You analyze inventory. You measure fan behavior. You optimize.
Eventually somebody discovers that a supporter has loved the Lakers since he was six years old and thinks: We can probably improve monetization here.
That sentence contains most of the next twenty years of American sports.
PABLO WAS RIGHT. I THINK IT GETS WEIRDER.
Pablo Torre has examined how private equity and soaring franchise valuations are changing the relationship between fans and their teams.
He is right about the transformation.
But private equity may ultimately be only one character.
The larger phenomenon is financialization: private credit, sovereign wealth, institutional minority stakes, stadium districts, global media rights, international games, sports betting, dynamic ticketing, premium inventory, fan data and lifetime customer value.
It is the conversion of sporting culture into an expanding collection of measurable financial rights.
The unsettling part is not that investors misunderstand why people love sports. It is that they understand it extremely well.
They understand loyalty, tribalism, scarcity, inheritance and the strange permanence of a relationship that often begins before a person is capable of making an informed decision.
If your father carried you into a stadium at five, you cried over the team at sixteen and you carried your own child into that same stadium at thirty-eight, switching costs are rather high.
Every terrible owner in sports history understood the most important thing instinctively:
You aren't going anywhere.
MAYBE DON'T FIX EVERYTHING
There is a story capitalism tells about itself in which markets identify inefficiencies and eliminate them.
Usually this is good.
Sometimes the inefficiency is the thing.
A neighborhood bar is inefficient compared with a national chain. A bookstore is inefficient compared with Amazon. A weird downtown stadium is inefficient compared with a fully integrated suburban entertainment district containing a sportsbook, hotel, luxury condominiums and seventeen restaurants that all somehow serve short ribs.
Human beings nevertheless have an irritating habit of becoming attached to inefficient things.
Sports may be especially vulnerable because almost everything people treasure about them is economically strange.
We care about laundry. We form emotional relationships with buildings. We hate people because their fathers attended a different university. We remember meaningless games because we watched them with someone who is no longer alive.
None of this survives discounted-cash-flow analysis particularly well.
And yet all of it contributes to why these assets are now worth billions.
That is the paradox beneath the modern sports economy:
The financial value exists because people care about something other than financial value.
The fan supplies the irrationality. The investor captures the return.
Sports spent more than a century constructing institutions people would refuse to abandon even when the underlying product disappointed them. Finance looked at that devotion and, quite reasonably, saw perhaps the greatest customer-retention story ever told.
There is probably no stopping the optimization. Nor should every attempt be stopped. Teams are businesses. Players should be paid. Capital can build things. Professional management can improve terrible organizations. Anyone nostalgic for some supposedly innocent sports economy should spend fifteen minutes reading about how owners treated players in 1974.
But maybe every square foot doesn't need yield.
Maybe every tradition does not require a presenting sponsor.
Maybe the old guy in Section 312 is not an under-monetized customer segment.
Maybe he is just the old guy in Section 312.
Sports became extraordinarily valuable because generations of people loved them irrationally.
They loved bad teams and bad stadiums and bad trades. They loved uniforms and radio calls and seats their fathers sat in and rivalries built from grievances nobody remembers anymore.
They loved something that could not be justified by economics.
And now economics has arrived to price it correctly.
God help us.
Because the moment someone asks for the lifetime value of a fan, he has understood the economics of fandom perfectly.
He has simply forgotten why anyone became a fan in the first place.
 Brief
The Comments
0 ON THE RECORDPredictions and premature victory laps may inspire future coverage.